You know the household is in good shape. You also know that if your spouse were suddenly unavailable, you would not be sure which account pays the property tax, where the latest trust document is stored, or who to call before making a financial decision.
That does not mean you have failed at the household finances. Couples divide responsibilities. The problem appears when division of labor quietly becomes a single point of failure.
The less-involved spouse does not need to become a second portfolio manager. The useful goal is simpler: know what exists, know how the household runs, know what authority is in place, and know the first people to call.
Define readiness as access and orientation
Start by separating three ideas that often get bundled together:
- Awareness: knowing that an account, obligation, document, or professional relationship exists.
- Access: being able to retrieve records, contact the institution, and use the household’s established security process.
- Authority: having the legal or contractual ability to act.
One does not automatically create the others. A spouse may know about an individual retirement account but have no present authority over it. A beneficiary may receive an account after death but have no access during incapacity. A trusted contact may be called by a brokerage firm but generally does not control the account.
The handoff plan should label each item clearly rather than relying on “we’re married” as the operating instruction.
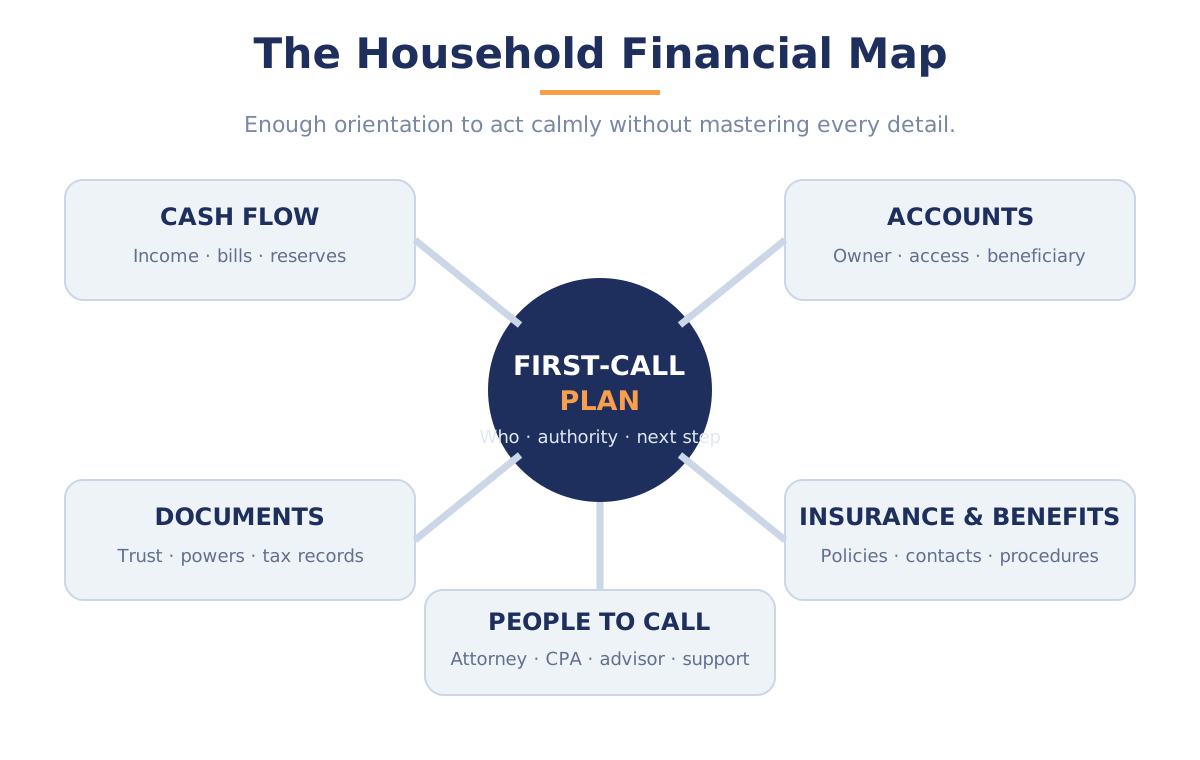
Build a one-page household financial map
The map is an index, not a balance sheet for the kitchen counter. It should show where the detailed records are stored and how to find them.
Include:
- bank, brokerage, retirement, benefit, credit, loan, and major property relationships;
- the legal owner and beneficiary status where applicable;
- recurring income and the account where it arrives;
- major bills, automatic payments, and the account that funds them;
- insurance policies and renewal contacts;
- tax preparer, estate attorney, financial advisor, and other key professionals;
- the location of wills, trusts, powers of attorney, health-care documents, tax returns, and property records; and
- the household’s approved method for accessing credentials and security devices.
The CFPB recommends organizing important documents, account and debt information, insurance, benefits, and professional contacts so they can be located in an emergency. The value is not the binder itself. It is the reduction in uncertainty when time and attention are already strained.
Walk through one month of cash flow
Investment statements are not the best place to begin. Start with the household operating system.
Together, trace:
- income deposits and benefit payments;
- mortgage, rent, property tax, association, and utility payments;
- credit cards and other recurring obligations;
- insurance premiums;
- estimated or withholding tax payments;
- transfers used to fund regular spending; and
- the reserve available if an account is temporarily restricted.
Then identify which payments are automatic, which require action, and which could pause without immediate harm. A surviving or caregiving spouse should not have to reverse-engineer the household from a month of notifications.
Our related article on the successor trustee’s first steps explains why authority and recordkeeping should come before moving or distributing assets after a death.
Confirm access without weakening security
“The password is somewhere” is not an access plan. Neither is casually sharing credentials in a way that conflicts with an institution’s terms or makes the household easier to defraud.
Review:
- whether each spouse has an individual login where the institution supports it;
- where password-manager recovery information and multifactor-authentication devices are kept;
- whether email, mobile phone, and primary devices can be accessed under the household’s documented plan;
- who receives alerts and statements;
- which bills depend on a card or account held in one name; and
- how to contact the institution if the primary user cannot respond.
Practice retrieving a statement and locating the service number. Do not wait for a crisis to learn that the security code goes to an inaccessible phone.
Match the legal document to the actual role
Authority can come from account ownership, a power of attorney, a trust, a court appointment, or an institution-specific arrangement. Those roles are not interchangeable.
Ask the estate attorney to review whether the current documents still reflect the household’s wishes and assets. Confirm who may act during incapacity, who serves after death, whether successor roles are current, and how institutions are expected to recognize the authority.
Social Security follows its own representative-payee process. Its advance-designation program allows an eligible person to identify possible future payees, but the agency states that the designation is optional, is not a power of attorney, and is not itself an appointment. Benefit-specific procedures belong on the map instead of being assumed from the estate documents.
Use trusted contacts for the role they actually serve
A trusted contact can give a financial institution another person to call if it cannot reach the account owner or sees circumstances that may warrant concern. It generally does not give that person authority to transact or access money.
Review the trusted contacts and emergency contacts on relevant accounts. Confirm that the people are still appropriate, understand the purpose, and can reach the household’s actual decision-makers. Keep the authority documents separate and current.
The CFPB also provides consumer resources on fraud and financial exploitation. The planning point is not to assume that every unusual event signals a problem. It is to create a clear reporting and verification path before pressure or confusion enters the picture.
Record the people to call—and the decisions that can wait
The financial map should end with a short first-call sequence:
- estate attorney for authority and document questions;
- CPA or tax advisor for filing, ownership, and payment questions;
- financial advisor and custodians for account access and cash-flow coordination;
- insurance professionals for claim, premium, and coverage procedures;
- benefit agencies for their separate reporting and representative processes; and
- a trusted family or support person identified by the household.
Beside that list, record which decisions should not be rushed. A health event or death may require immediate bills, notifications, and account continuity. It does not automatically require a new portfolio, a home sale, or a large distribution.
The goal is not equal enthusiasm for finance. It is a household that can still function when one person cannot run the usual system.
Practice one annual handoff conversation
Once a year, switch roles for a short, practical exercise. The spouse who usually handles the finances should observe while the other spouse:
- opens the financial map;
- retrieves a bank and investment statement;
- identifies the next month’s major payments;
- locates the legal documents;
- names the first three professional calls; and
- explains where near-term cash is available.
The exercise is not a test. Anything that is hard to locate, explain, or access becomes the next improvement to the system.
What to consider next
Choose one quiet hour before there is an emergency. Build the first version of the map, walk through one month of cash flow, and identify the largest access or authority gap. Then have the attorney, CPA, financial advisor, insurance professional, and benefit agencies verify the parts within their roles.
Keep sensitive details in the household’s designated credential and document systems rather than the one-page index. Set a calendar date for the next review and update the map whenever an account, document, professional, device, or benefit changes.
A useful handoff plan does not ask one spouse to become the other. It gives both people enough clarity to maintain continuity, ask informed questions, and avoid irreversible decisions until the facts and authority are organized.
Sources
- Organizing financial documents, contacts, trusted contacts, and authority before illness or diminished capacity — Consumer Financial Protection Bureau, Planning for diminished capacity and illness
- Consumer resources for trusted contacts and financial-exploitation awareness — Consumer Financial Protection Bureau, Protecting Older Adults from Fraud and Financial Exploitation
- Advance designation of a possible future representative payee is optional and is not a power of attorney or an appointment — Social Security Administration, Advance Designation of Representative Payee
- California statutory framework for powers of attorney — California Legislative Information, Probate Code Division 4.5